How Much Money Do I Really Need for Retirement?

Ravi walked into Shyam’s office holding a cup of chai, looking a bit tired. He turned 55 last week.
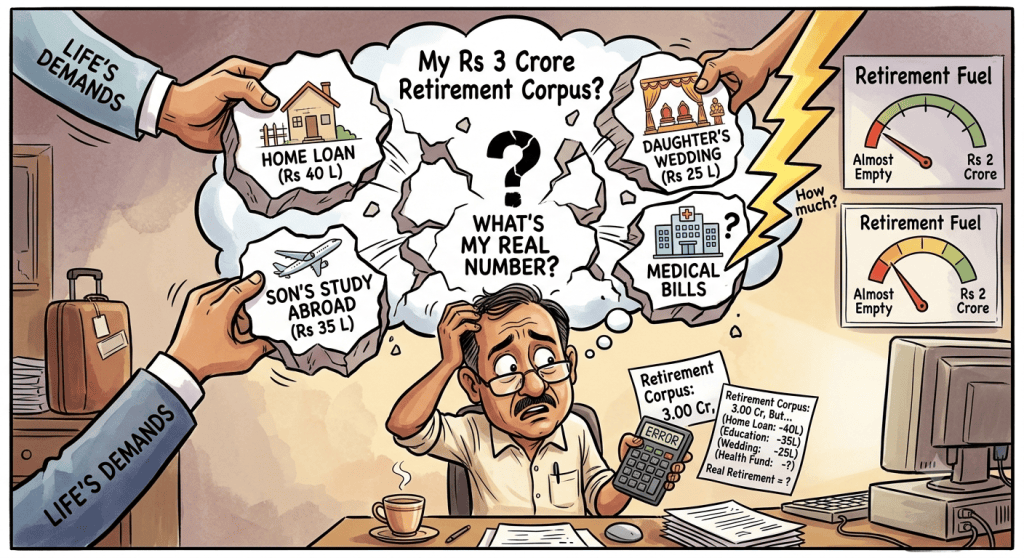
Ravi: Shyam bhai, I have saved Rs 3 crore. I want to stop working at 60. Is that enough?


Shyam: Good that you’re asking now, not at 60. First tell me — what does your house spend every month? Like, if you add up groceries, electricity, maybe a movie or two.


Ravi: Around Rs 90,000. Simple life. No rent, since the house is paid off.


Shyam: Okay, here’s an easy trick. Take that monthly number and multiply it by 350. Think of it like buying enough “fuel” to run your life for many years without stopping at the pump too often.


Ravi: 90,000 times 350… that’s about Rs 3.15 crore. I have Rs 3 crore. So I’m almost there?


Shyam: Almost. But there’s a second rule. Don’t take out more than 6 rupees for every 100 rupees you have, each year. It’s like a water tank — if you keep the tap too open, it runs dry fast. Keep it just right, and it refills a little every year even while you’re using it.


Ravi: Okay, sounds manageable.


Shyam: Now let me ask something that stings a bit. That Rs 3 crore — is all of it really for you?


Ravi: What do you mean, it’s my money.


Shyam: Think of it like your fridge. It’s your fridge, but if half of it is already packed with food for a family function next week, is it really “your” fridge for daily use right now? Let’s check. Any loan still running?


Ravi: Yes. Home loan, another 8 years to go. About Rs 40 lakh left.


Shyam: Your son?
Ravi: Wants to study abroad in three years. We already told him yes. That’s around Rs 35 lakh.
Shyam: Daughter’s wedding?


Ravi: (smiles awkwardly) Yes… we’ve been quietly saving for that too. Maybe Rs 25 lakh.


Shyam: So add it up — Rs 40 lakh, Rs 35 lakh, Rs 25 lakh. That’s Rs 1 crore already “booked,” like seats reserved on a train before you even reach the station. What’s actually free for you?


Ravi: Rs 2 crore.


Shyam: Right. And Rs 2 crore is not 350 times your monthly spend anymore — it’s closer to 220 times. So the number that looked comfortable on paper was already half-promised to other people. It was never fully yours to relax with.


Ravi: That’s a bit of a wake-up call.


Shyam: It usually is. But it’s better to know now than to find out at 70. Just write down everything you’ve promised — loans, weddings, kids’ education — and subtract it honestly. Whatever remains, that’s your real number.


Ravi: Understood. What else should I know?


Shyam: Health. Tell me — is a hospital bill part of your Rs 90,000 monthly budget?


Ravi: No, that’s separate. We have insurance.


Shyam: Good start, but insurance is like an umbrella — it helps, but it doesn’t always keep you fully dry in heavy rain. Say your father needs heart surgery. Bill comes to Rs 15 lakh. Insurance covers Rs 6 lakh. Where does the remaining Rs 9 lakh come from?


Ravi: From my savings, I guess. My retirement money.


Shyam: That’s what most people do, and here’s the surprising part. Even if you’re careful and only withdraw your usual 6%, that one big bill quietly makes your yearly income smaller for many years after — like a bruise that doesn’t hurt every day, but slows you down for a long time. You don’t go broke. You just live a little tighter, every single year, without knowing exactly why.


Ravi: That sounds like something that could sneak up on anyone.


Shyam: Exactly. So I tell people to build three simple layers, like keeping three different pockets. Pocket one — good health insurance with a top-up, so bigger bills are covered better. Pocket two — a separate medical fund, kept apart from your retirement money, just for these moments. Pocket three — a credit card with a high limit or a ready credit line.


Ravi: Why the credit card if I already have a medical fund?


Shyam: Because hospitals don’t ask if the stock market is having a bad week. If you’re forced to sell your investments during a market dip just to pay a bill, you lose more than you should. The credit line buys you three or four weeks — like a short bridge — so you can calmly move money from your medical fund instead of panic-selling.


Ravi: Makes sense. Now, how many years should I actually plan for? I was thinking maybe 25 years after retirement.


Shyam: Here’s a simple way to think about it. If you’re healthy at 60, you’ve already crossed many hurdles that shorten the “average” life expectancy number — accidents, early illness, and so on. So your real number is likely longer than the average. Plan for 30 to 35 years, not 20 or 25. Think of it like packing for a trip — better to carry a little extra than run short halfway.


Ravi: And what about my wife?


Shyam: Plan around whoever is likely to live longer, not an average of both of you. Women usually live a couple of years more than men on average. So if it’s likely she outlives you, her retirement plan should be sized for her — not shortened to match yours.


Ravi: Shyam, I came in feeling confident, and now I have a proper to-do list.


Shyam: That’s a good place to be. None of this needs a finance degree — just honesty with yourself. List what you’ve promised others. Subtract it. Build your three health pockets. And plan for more years than feels comfortable. Do this, and the number you retire will truly be yours to enjoy.


Ravi: (smiling, finishing his chai) Alright. Let’s make that list together.
Patience Pays Interest: A Journey Back to Discipline

Ravi: Shyam, it’s been a while. You look lighter today — last time we spoke, you were carrying the weight of the world on your shoulders. What changed?

Shyam: Ravi, I have a story to tell you. Do you remember why I first came to you, worried?

Ravi: Of course. You’d been in your job for close to eight years, steady and stable, but your salary had barely moved — under four percent a year. And you still had seventeen years left on your home loan.

Shyam: Exactly. I’m in my mid-forties now, and that math kept me up at night. A loan running into lakhs, a raise that couldn’t even keep pace with inflation, and time slipping by. I felt stuck.

Ravi: So you went looking for a shortcut.

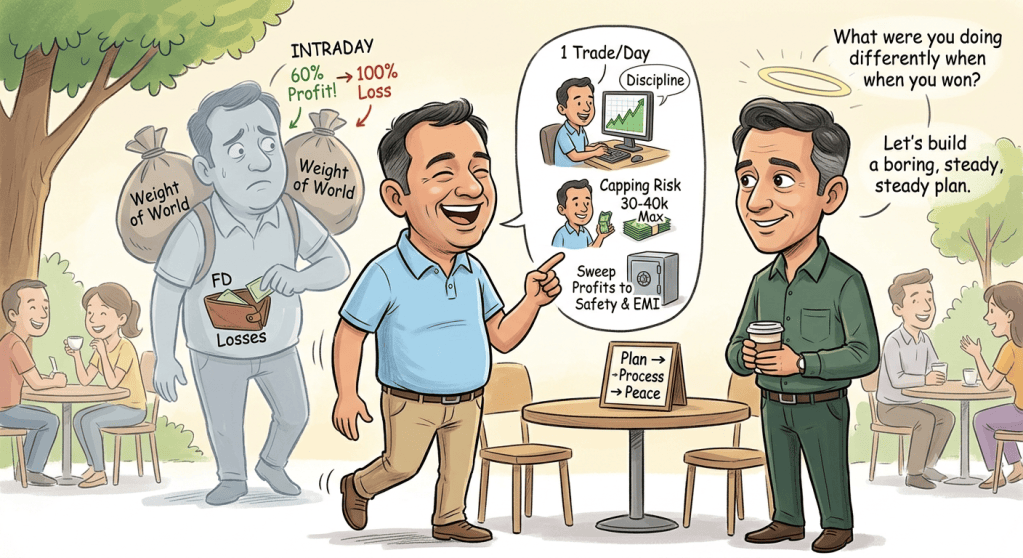
Shyam: (laughs, a little embarrassed) I did. Someone told me intraday trading could fetch quick returns. I put in one lakh rupees — just to “try.” And in the first few weeks, I made sixty percent returns. Sixty percent, Ravi! I thought I’d finally found the answer.

Ravi: I remember that phase. You were buoyant, calling me to ask why you should bother with mutual funds and SIPs when you could make that kind of money in weeks.

Shyam: And then it all came apart. I got greedy, started trading more, chasing bigger positions. In a single week, I lost every rupee of profit I had made. It didn’t stop there — I broke my fixed deposits to cover the losses, and even that money kept getting eaten up. The losses were compounding faster than I could plug them.

Ravi: That was a hard time. You told me you wanted to quit — not just trading, but almost quit believing in yourself.

Shyam: I did feel very low. That’s actually when I came to you, remember? I was ready to walk away from the markets altogether.

Ravi: I remember. But instead of telling you to quit, I asked you a simple question — “Before you had losses, you had a few weeks of real profit. What were you doing differently then?” I wanted you to go back and study your own winning trades, not just the losing ones.

Shyam: That question stayed with me. I went back through my trade log from those first few weeks and looked closely.

Ravi: And what did you find?

Shyam: Discipline, mainly. In those early weeks, I wasn’t trading all day. I’d research one stock in the morning, take a single trade, and stop — win or lose. Once I started overtrading later, chasing every small movement and taking five or six trades a day, that’s exactly when it fell apart.

Ravi: That’s the clue I was hoping you’d find. One good, researched trade a day was your actual edge. The moment you turned it into all-day speculation, the edge disappeared and emotion took over.

Shyam: So we rebuilt my approach around that one insight.

Ravi: Yes, but I also insisted on one more rule, because insight alone doesn’t protect you from yourself in a bad week. I told you: ring-fence your trading capital. Keep a fixed amount — say thirty or forty thousand rupees — set aside purely for intraday trading. Every other rupee of your income, your savings, your EMI money, stays completely separate and untouched. That way, the worst that can ever happen is you lose that fixed thirty or forty thousand. Never more.

Shyam: That changed everything for me psychologically. I wasn’t trading with the fear of touching my FDs or EMI money anymore, because I’d already decided the maximum damage was capped. Within that fixed pool, I traded just once a day, only after some research, happy with two to four thousand rupees. No greed, no revenge trading.

Ravi: And the second habit I asked you to build?

Shyam: Every single day, whatever profit I made, I moved it out of the trading account immediately into a liquid fund or an overnight fund. The profit never sat there tempting me to “let it ride” the next day.

Ravi: That’s the part that impressed me most. You didn’t just find a strategy — you built two guardrails around it: a hard cap on capital at risk, and a same-day sweep of profits to safety.

Shyam: Between the fixed thirty-to-forty-thousand cap, the one-trade-a-day rule, and sweeping profits out daily, I built up thirty-eight thousand rupees in the very first month, which I pulled out and used toward my EMIs. And I kept at it — patiently, consistently, within that same fixed capital — for two years.

Ravi: Two years of showing up, staying inside a fixed capital, taking one measured trade a day, and sweeping the gains to safety. That’s not luck, Shyam. That’s a system — one we built together after your worst week.

Shyam: I couldn’t have found it alone, Ravi. If you hadn’t asked me to go back and study my own winning trades instead of only mourning the losses, and if you hadn’t insisted on that fixed thirty-to-forty-thousand cap, I think I’d have either quit the markets out of fear, or kept doubling down until there was truly nothing left. It taught me something I’ll carry for the rest of my life — there’s no easy money in the world of finance. None. But if you’re honest about your shortcomings, understand them fully, and then take a leap of faith with a measured, calculated approach — you really can do wonders.

Ravi: (smiling) That’s exactly the wisdom I wish every investor arrived at without having to lose their FDs first. You paid a costly tuition fee, Shyam, but you learned the real lesson: markets don’t reward impatience or greed. They reward process, a hard cap on what you’re willing to risk, and protecting what you’ve already earned.

Shyam: So where do I go from here? I still have seventeen years on this loan.

Ravi: Now that you’ve proven to yourself you can be disciplined, let’s bring that same discipline to your whole financial picture — your EMIs, your emergency fund, your long-term investments, even that one trade a day if you still enjoy it, but as a small satellite, never the core of your plan. The core has to be boring, steady, and built for seventeen years, not seventeen days.

Shyam: Boring sounds good to me now, Ravi. I’ve had enough excitement for one lifetime. And do you realize — thirty-eight thousand a month, sustained for two years, meant I pushed close to nine lakh rupees extra towards my home loan in that time. Money that would never have come my way through a four percent annual raise.

Ravi: That’s the real proof, Shyam. Almost nine lakh rupees shaved off a seventeen-year loan, built purely through discipline, a fixed cap on risk, and patience — not through any miracle strategy.

Shyam: I want to thank you for that, Ravi. Not just for the numbers, but for not letting me walk away when I was at my lowest. You could have simply told me to quit trading altogether. Instead, you asked me the right question, gave me the guardrails I needed, and stood by me while I rebuilt everything, one disciplined trade at a time. I don’t think I’d be standing here today, this much closer to being debt-free, without you.

Ravi: (smiling) That’s what I’m here for, Shyam. My job was never to give you a shortcut — it was to help you turn your own hard-earned lesson into a system you could trust. You did the discipline. I just helped you see it clearly.

Shyam: (laughs) Then let’s build the rest of this boring, unshakeable plan together.

Disclaimer: This is a fictional, illustrative story created for educational purposes only. It does not constitute financial, investment, or trading advice. Intraday trading carries a high risk of loss and is not suitable for everyone. Past performance, including any figures mentioned here, is not indicative of future results. Please consult a SEBI-registered financial advisor before making any investment or trading decisions.

That ₹99 Charge Isn’t the Problem. It’s Everything Else You Forgot About.

Last week, I got an email about a “storage plan update” for my cloud account. My first thought?

Delete.

But I opened it anyway.
Turns out my bill would go up by a few rupees. That’s it. Barely anything.


And that’s exactly why these emails work on us. Nothing ever feels big enough to worry about.
We Don’t Notice “Small”


Think about your phone right now. Netflix. Hotstar. Spotify. Maybe extra cloud storage. A food app membership. That fitness app you downloaded on January 1st and forgot about by February.


Each one costs ₹99, ₹149, ₹199. Small enough that you never really decide to keep paying. You just… do.


UPI makes this worse. Payments happen so fast, so quietly, that a ₹149 auto-debit gets lost between 20 other notifications. You glance at your balance, it looks fine, you move on.
Small Charges Add Up to Something Big
One ₹149 subscription?

No big deal.


But nobody has just one.

Most of us have eight or ten — two OTT apps, extra cloud storage, a recharge plan with extras you don’t use, some app you tried once and never cancelled.


Add it up: ₹150–₹300 each, times ten. That’s ₹1,500–₹2,500 every month. Over a year? ₹20,000–₹30,000 — gone, without ever feeling like a real expense.


These Charges Are Little Time Capsules
Here’s the thing — every subscription tells a story about who you were when you signed up. The you who swore you’d use that language app daily. The you who needed extra storage for last Diwali’s photos you haven’t opened since.


Going through your subscriptions isn’t just about saving money. It’s a quick check-in: does this still match who I am now?


Try This — It Takes 10 Minutes.


Open your UPI app (PhonePe, Paytm, or any other) and find “AutoPay” or “Mandates.” Most people don’t even know this list exists. It shows every single recurring payment in one place.
Once every 3 months, scan your bank statement for anything under ₹300. That’s where the sneaky stuff hides.


Ask yourself: “Would I sign up for this today?” If not, cancel it. No guilt needed.


Next time you get a “plan update” email, actually read it. It’s often the only time anyone tells you what you’re really paying for.


The Bottom Line : Managing money well isn’t just about the big stuff — your SIP, your insurance, your EMI. It’s also about catching the small leaks before they become a habit.


That ₹99 charge won’t ruin you. But ignoring ten of them, year after year? That adds up quietly — because unlike your bank app, your attention never sends you a low-balance alert.

Rice, Dal, and Fixed Deposits: What a “Portfolio” Really Means

Shyam walked into Ram’s office with a cup of chai and a confused face. He had just started earning a good salary, and everyone around him kept saying “build your portfolio, build your portfolio.” He had no clue what that meant.

Shyam: Ram, what is a “portfolio”? People keep using this word and I just nod along.


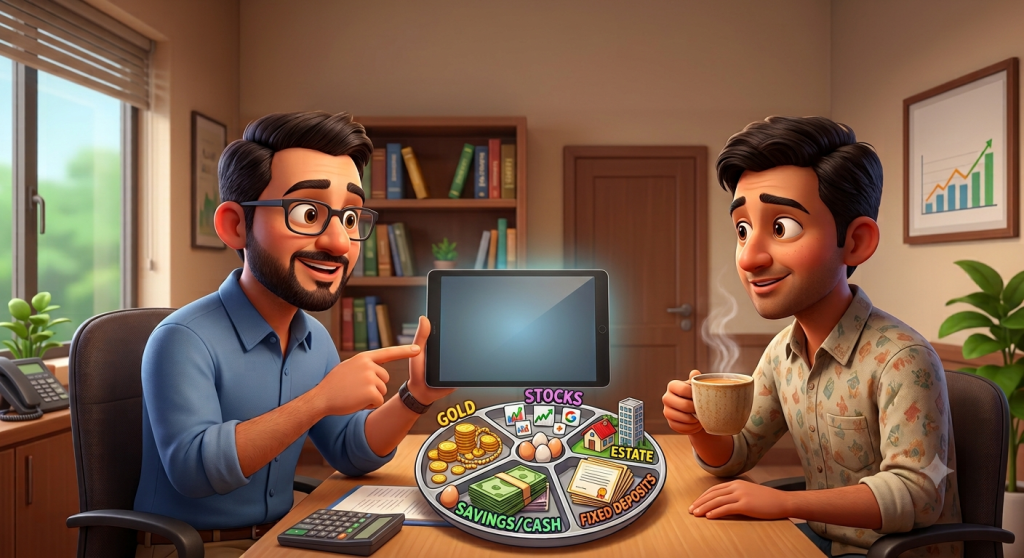
Ram: No problem, let’s make it simple. Think about your kitchen. You don’t keep only rice at home, right? You keep rice, dal, vegetables, oil, spices — a mix of things. Your portfolio is just like that, but for your money. It’s all the different places you’ve put your money — savings account, fixed deposit, gold, stocks, mutual funds, maybe even a house. Put them all together, and that’s your portfolio.
Shyam: Oh! So if I have money in a savings account AND a fixed deposit, that’s already a portfolio?


Ram: Yes! Even two items make a portfolio. It’s not about having a huge amount of money. It’s simply about what mix of things you own.
Why not just put all my money in one place?


Shyam: But Ram, why should I spread my money around? Why not just find the one best investment and put everything into it?


Ram: Good question. Let me give you an example. Suppose you only eat one dish every single day — say, only rice. Some days it’ll be fine. But if one day there’s no rice available, you’ll go hungry. Now imagine you eat rice, roti, and vegetables on rotation. If one is missing, you still have something to eat.
Money works the same way. Some years, the stock market does really well. Other years it crashes. Gold might just sit quietly for years and then suddenly jump in value when everything else is falling — like during a crisis. If you keep money in different places, when one is down, another might be up. This balancing act is called diversification. In simple words: don’t put all your eggs in one basket.


Shyam: So it’s like not keeping all my emergency cash in one wallet, in case I lose that wallet?

Ram: Exactly like that!

Shyam: Okay, so what are my basket options?


Ram: Here are the main ones, with everyday examples:
Equity (stocks/mutual funds) — Like investing in a friend’s shop that’s growing fast. It can give you great returns, but if the shop has a bad month, your money can also go down. Higher risk, higher reward.
Debt (fixed deposits, bonds) — Like lending money to your reliable cousin who always pays you back with a little interest, on time, every time. Safe and predictable, but the growth is slow.
Gold — Like the gold your mother keeps for emergencies or weddings. It doesn’t grow fast, but it holds its value when everything else feels shaky.
Real estate — Like buying a flat and renting it out. It can grow in value over the years, but you can’t sell it quickly if you suddenly need cash.
Cash / savings account — Like keeping some money under the mattress (but safer, in the bank) for emergencies — a medical issue, a job loss, urgent travel.


Shyam: So my portfolio is really just “how much money I’ve put in each of these buckets”?


Ram: Exactly right. That mix — how much in stocks, how much in FDs, how much in gold — is called your asset allocation. This one decision matters more than picking the “best” stock or fund. It decides how fast your money grows and how much it will bounce up and down along the way.
What does having a portfolio actually mean for me?


Shyam: Okay, so in real life, what does this mean for someone like me?


Ram: A few simple things, Shyam, it depends on your goals. Saving for a bike next year is very different from saving for retirement 30 years from now. Short goal, safer mix. Long goal, you can take more risk.
It depends on how much risk you can handle. If seeing your investment drop 10% in a month makes you lose sleep, you need a calmer mix — more FDs, less stocks. If you can stay calm and wait it out, you can take more stock market exposure.


It’s not a one-time task. Just like you don’t buy groceries once a year and forget about it, your portfolio needs occasional check-ins. A new job, marriage, a baby, buying a house — all of these are reasons to relook at your mix.
Judge the whole basket, not one item. Don’t panic if one stock in your portfolio falls. Look at how your entire basket is doing, the same way you’d judge a meal by the whole thali, not just one vegetable.


Shyam: That actually makes me feel much better. I thought I had to become some stock market expert overnight.


Ram: Not at all. It’s less about picking “winners” and more about balance and patience — building a mix that fits your life, not your colleague’s or your neighbour’s.


Ram’s one-line takeaway for Shyam


Ram: If you remember just one thing — a portfolio is not a random pile of investments. It’s a thoughtfully mixed thali of your money, built around your goals and how much risk you’re comfortable with.


Shyam: So my first step is figuring out my goals and comfort with risk — not chasing the “hottest” stock tip from my WhatsApp group.


Ram: Now you’re thinking like an investor, not a gambler.

Disclaimer:This piece is for general learning purposes only and isn’t personal financial advice. Everyone’s goals and risk comfort are different — it’s best to talk to a qualified financial advisor about your own situation.

Global Asset Allocation for Optimum Returns — Your Portfolio’s Missing Piece

A conversation more about balance, not bets.

“Shyam, Is My Portfolio Really Complete?”

Diya had been investing for nearly eight years. Disciplined SIPs, a solid mix of large cap and flexi cap funds, some gold on the side. Every month, without fail, the money went in. She was proud of that.

But sitting across from her financial planner Shyam one evening, she couldn’t shake a quiet unease.

“Everything looks fine on paper,” she said, scrolling through her portfolio. “But somehow it doesn’t feel complete.”

Shyam nodded. He knew exactly what she meant.

“Diya, can I ask you something first?”
“Sure.”
“How many years have you been investing?”
“Eight years. Almost nine.”

“And in those eight years, have you ever had a year where you felt your portfolio was working really hard — and another year where it just felt stuck?”

She laughed. “Last year was great. This year…” she trailed off.

“This year Nifty is down. And that’s perfectly okay — that’s how markets work. India’s growth story is absolutely intact. The demographics, the infrastructure push, the consumption boom — none of that has changed. Your core Indian portfolio is doing exactly what it should be doing over the long term.”

Diya looked slightly relieved.

“But here’s my question,” Shyam continued. “While your portfolio was stuck this year — do you know what was happening outside India?”

She shook her head.

Shyam turned his laptop around. A simple heat map. Country by country, year by year, showing which market led and which lagged over twenty-one years.

“Look at this. No single country has stayed on top for more than a few years at a stretch. America dominated one window. China exploded and then crashed. Japan surprised everyone. Taiwan came out of nowhere recently. India had its own brilliant phases.”

“So they all take turns,” Diya said.
“Exactly. And here’s the one number I want you to remember — over the last twenty-one years, the US S&P 500 has delivered roughly thirteen and a half percent annually when measured in Indian rupees.

Nifty 50 delivered around 12% over the same period. Almost identical returns. But one was happening entirely outside India, in different companies, different sectors, a completely different economic cycle.”

Diya leaned forward.

“So the returns are similar, but they don’t move together.”
“Now you’ve got it.”
“So what are you suggesting?” she asked. “That I move out of India?”
“Absolutely not,” Shyam said firmly. “Your India story is your foundation. Don’t touch it. 80 to 85% of your portfolio should stay exactly where it is — in the funds you trust, the SIPs you’ve built, the India growth story you’ve been backing for 8 years.”

“Then what are we talking about?”
“The remaining ten to twenty percent. That’s the conversation.”

He leaned back.

“Think of your portfolio like a house. Right now it’s beautifully built — solid walls, great structure, everything you need. But it has only one window. And that window faces India. What I’m suggesting is that you open one more window. Not to leave the house. Just to let in more light.”

Diya smiled at the analogy. “Okay. So what’s outside that window?”
“Companies and themes that simply don’t exist at scale on Indian exchanges. The technology that powers every smartphone on the planet. The chips that run artificial intelligence. The software platforms that a billion people use every single day. These are businesses growing at a pace that is genuinely hard to find anywhere else right now.”

“And Indian investors can access all of this?”
“Completely. Through simple mutual fund routes — no foreign accounts, no complexity. Your money goes in as rupees, it works internationally, and it comes back as rupees. Same SIP process you already know.”

“What does this actually do for my portfolio?” Diya asked.

Shyam picked up a pen.

“Three things. First, it smooths your journey. When Indian markets are going through a tough phase — like right now — that ten to twenty percent is potentially working hard elsewhere, cushioning the overall impact.”
“Like a shock absorber.”

“Exactly. Second, there’s a natural currency benefit. The rupee has historically weakened gradually against the dollar over time. So your international returns get a quiet boost just from that movement — without you doing anything.”

“And third?”

“You get exposure to the next big wave before it fully arrives in India. AI, semiconductors, global healthcare innovation — India will eventually benefit from all of these, but the companies building the core infrastructure are mostly listed abroad. Owning a small piece of that story early is just smart investing.”

Diya was quiet for a moment, looking at her phone screen — her portfolio, eight years of careful decisions staring back at her.

“I’ve spent so much energy choosing between large cap and mid cap, between growth and value, between fund A and fund B — all within India. I never once thought about whether I needed to step outside at all.”

“Most investors don’t,” Shyam said gently. “And honestly, the fact that you’ve stayed disciplined and kept investing through every market cycle — that’s the hardest part. You’ve already done the difficult work.”
“This is just the next chapter,” Diya said quietly.
“Exactly that. You’re not changing your story. You’re just making it a little bigger.”
She put her phone down and looked at him.

“10 to 20% Outside India. As a shield, not a shift.”
“That’s all it is,” Shyam said. “You keep everything you’ve built. You just add one layer of balance that works when your core portfolio needs a breather.”
Diya nodded slowly, the unease from earlier finally lifting.

“Why did nobody tell me this eight years ago?”

Shyam smiled.

“Better late than never. The good news is — you have decades of compounding still ahead of you. And now your portfolio is ready for all of them.”

This is a fictional conversation created for illustrative purposes and does not constitute investment advice. Please consult a SEBI registered financial advisor before making any investment decisions.

Disclaimer : For informational purposes only. This is not investment advice. Mutual fund investments are subject to market risks. Please consult your registered financial advisor before making investment decisions. Read all scheme related documents carefully before investing.

Your Money Is Quietly Leaving the Country. Here’s What To Do?

Siya: Ram, I have to be honest — I’ve been losing sleep over my portfolio. I keep hearing that the stock market has lost a massive amount of value. Is it really as bad as it sounds?

Ram: I understand the anxiety, Siya. The numbers are big, and they sound scary. The market has lost a very significant chunk of its total value compared to its all-time highs — we’re talking somewhere in the range of 17% to 20% of the country’s entire annual economic output, just gone from stock market valuations. So yes, it’s real. But before you panic, let’s talk about why this is happening, because that matters more than the number itself.

Siya: Okay. Everyone around me is saying it’s because of rising oil prices and global tensions. Is that true?

Ram: That’s the popular explanation, and it’s partly right. But here’s the thing — if oil prices were the only reason, then every country that imports most of its oil would be suffering similarly, right? And that’s not quite what we’re seeing. The deeper problem is something most people aren’t talking about: foreign investment flows.

Siya: Foreign investment? What do you mean exactly?

Ram: Let me give you a simple picture. A few years ago, foreign money was flowing into our markets in huge amounts — tens of billions of dollars ($) every year. That money was supporting company earnings, keeping the currency strong, and pushing the stock market higher. But over time, the gap between money coming in and money going out has been shrinking. And in the last couple of years, there’s been almost no net foreign investment left.

In fact, we’ve been losing more than we’re gaining.

Siya: So money is leaving the country?

Ram: Yes. On two fronts. First, large foreign investors who came in during the boom years are now taking their profits and moving to other opportunities — which is normal behaviour in a mature market, but it puts pressure on us. Second, our own companies are investing abroad in large amounts — tens of billions of dollars ($) — because certain other countries offer lower taxes and simpler regulations.

Siya: And this is affecting the rupee (₹) too? I noticed my international transactions feel more expensive lately.

Ram: Absolutely. This is one of the clearest signs of the problem. The rupee (₹) has been weakening — not just against the dollar ($), which you might expect, but also against the currencies of smaller neighbouring economies. That tells you it’s not just a global dollar ($) story. When foreign investment dries up, demand for the rupee (₹) falls, and it depreciates. It’s like the price of anything — if fewer people want it, it gets cheaper.

Siya: This is worrying. So what is being done about it?

Ram: Regulators are aware. There are efforts underway to make the market more accessible and investor-friendly — easing certain rules, conducting currency swap auctions to shore up foreign reserves. These are technical measures, but they signal that the issue is being taken seriously. The fix, though, isn’t overnight. Attracting investment back requires rebuilding confidence, improving the regulatory environment, and time.

Siya: While all this is going on, what should I be doing? I’m tempted to just pull everything out.

Ram: And that, Siya, is exactly the mistake I want to stop you from making. Let me tell you about the two biggest errors I see investors make in times like these.

Siya: Please, tell me.

Ram: The first mistake is having no cushion.

Most investors put everything into market-linked investments — mutual funds, stocks, ETFs — and nothing in safe, fixed-return options. When markets fall, they have no stable ground to stand on, so panic sets in. A simple rule of thumb: keep at least 10 to 15% of your portfolio in something that gives you a fixed, predictable return, like a fixed deposit or a recurring deposit. If you’re retired or close to it, that number should be much higher — closer to 75 to 85% in stable instruments.

Siya: I never thought about it that way. I always assumed fixed deposits were “boring money.”

Ram: Boring money is the best money when everything else is burning! It’s your financial shock absorber. And if putting a large lump sum aside feels difficult, a recurring deposit works beautifully — you put in a small, fixed amount every month, it builds the habit, and your money earns decent interest safely. Look for options where you can compare rates across multiple banks, and make sure your deposits are insured up to the regulatory limit so your money is protected even if a bank has trouble.

Siya: That makes sense. What’s the second mistake?

Ram: Panic selling your mutual funds. This is the one that costs people the most, and I’ve seen it happen again and again. The market dips 20, 25, even 30%. Investors can’t take the pain of watching their portfolio bleed on screen, so they sell. And then — almost always — the market recovers. The people who sold have now locked in a permanent loss, while those who stayed have recovered, sometimes fully.

Siya: I’ll be honest, I did look at my mid-cap fund last month and almost hit the sell button. The NAV had dropped almost 25% from its peak.

Ram: I know. It feels like the right thing to do in the moment. But think about it this way — you didn’t “lose” that money until you actually sold. On paper, a drop is just a number. The real loss happens when you exit at the bottom and then watch the recovery happen without you.

Siya: So I should just… hold?

Ram: Not blindly. There’s a difference between panicking and reviewing. If your fund has strong fundamentals — good historical performance across market cycles, a solid management team, a clear investment strategy — staying invested is almost always the right call during short-term volatility. But if you were in a fund that was already underperforming even in good times, a downturn is a good moment to review and possibly switch — calmly and deliberately, not out of fear.

Siya: This has been really helpful, Ram. So to summarize what you’re telling me: the situation is real but not catastrophic, there are bigger forces at play beyond just oil prices, and my job as an investor is to stay diversified, stay calm, and not make decisions out of panic.

Ram: Perfectly put. The economy and the market go through cycles.

The investors who build wealth over time are not the ones who got lucky predicting every dip — they’re the ones who stayed disciplined when it was uncomfortable. Keep some money safe, keep your long-term investments intact, review but don’t react, and you’ll be fine.

Siya: Thank you, Ram. I’m going to go set up that recurring deposit today.

Ram: That’s the best thing I’ve heard all week. Small, steady steps — that’s how real financial security is built.

**Have questions about managing your portfolio through market volatility? Drop them in the comments below.

Your Money Is Being Quietly Eaten — Here’s What’s Really Happening

Part 1 — The Big Picture

Shyam: Ram bhai, I’ve been hearing scary things — petrol prices rising, global tensions, gold going haywire. Should I be worried about my savings?

Ram: Shyam, you’re not alone. In the past few weeks alone, I’ve had dozens of investors sitting right where you are — panicking, questioning everything, and seriously considering moving all their money into fixed deposits or gold just to feel safe. The urge to run to safety is completely human. But before you make any move, let’s understand what’s actually happening — because reacting to noise without understanding it is often the most expensive mistake an investor can make.

Shyam: That’s exactly how I feel — like I just want to put everything somewhere safe and stop watching the numbers fall.

Ram: I hear you. But “safe” in the short term can quietly become “costly” in the long term. Let’s break it down step by step — once you understand what is happening and why, that fear starts to lose its grip.

Shyam: Please. Start from the beginning.

Ram: The root of most current worries is oil. Our country imports enormous amounts of crude oil. When tensions rise in oil-producing regions, global prices spike — and our import bill becomes very heavy very fast.

Shyam: But pump prices haven’t gone up yet. Isn’t that good?

Ram: Short term, yes. But someone is absorbing that extra cost — right now, it’s the government. They’re dipping into our national reserves — think of it as the country’s savings account — to cover the gap. That can’t go on indefinitely.

Shyam: So those reserves are shrinking?

Ram: Gradually, yes. These are called Forex Reserves — India’s emergency fund in foreign currency. They keep the Rupee stable and signal financial health to the world. With oil expensive and fuel prices unchanged, reserves are under pressure. The longer this continues, the more strain on the economy.

What are Forex Reserves? Our country’s foreign currency emergency fund — used to pay for imports like oil, gold, and electronics. When reserves fall, the Rupee weakens and imports get costlier, creating a ripple effect across the entire economy.

Part 2 — What Comes Next

Shyam: So what will the government do?

Ram: Eventually, they’ll likely raise petrol and diesel prices — passing the cost to consumers. Painful, but responsible. You simply cannot keep bleeding the national wallet. When that happens, inflation rises — fuel costs trickle into everything. Transporting vegetables, manufacturing goods, running businesses — all become costlier. Sectors like banking, housing, and automobiles slow down as people spend more carefully.

Shyam: What about gold? Why is the government asking people not to buy it?

Ram: Our country imports a massive amount of gold every year, all paid in foreign currency. Every gold purchase chips away at our reserves. Recently, import duties on gold were reduced significantly, which caused imports to surge. Now, to protect reserves, the government may raise those duties again — making gold costlier to import and slowing the drain.

Shyam: So gold stocks could fall further if duties go up?

Ram: Exactly. If duties rise, gold companies face pressure and stocks could drop more. If duties stay unchanged, the current dip is actually a buying opportunity in quality gold stocks. That duty announcement is the signal to watch.

Part 3 — The Stock Market

Shyam: My portfolio keeps falling. I keep hearing foreign investors are leaving the country. Is it that bad?

Ram: It’s real and significant. Foreign Institutional Investors — the big global funds — have been selling Indian stocks heavily. This is directly hurting your portfolio. But here’s the key — India hasn’t done anything wrong. It’s about global competition for money.

Shyam: What do you mean?

Ram: Think of it like two restaurants. Restaurant A offers solid, reliable food. Restaurant B just launched a dish everyone’s obsessed with and profits are extraordinary. Where does money flow first? Right now, the AI boom is Restaurant B — global investors are chasing extraordinary returns in markets with semiconductor and chip companies. Our country doesn’t have that story yet, so money flows there instead.

Shyam: Will foreign investors ever come back?

Ram: They will. Two triggers could bring them back fast — first, if the AI boom slows, funds seek the next opportunity and our country, with its strong growth projections, becomes very attractive. Second, any peace resolution in ongoing global conflicts. Markets reacted with sharp single-day gains just on ceasefire rumors — imagine a real, lasting peace deal.

The Silver Lining our country’s economic growth remains among the highest of any large economy globally. Foreign selling reflects competition for global capital — not a loss of faith in country’s fundamentals. The long-term story is very much alive.

Part 4 — What Should You Do?

Shyam: Enough about the problem. What do I actually do with my money?

Ram: Two answers — one for long-term investors, one for shorter-term moves.

For the long term: your most powerful weapon is patience. Our country has survived wars, recessions, crises, and pandemics. Every time, markets recovered and reached new highs. The investors who stayed calm and didn’t sell at the bottom built real wealth. Markets don’t rise every year — some years are flat or negative — but when recovery comes, it comes fast and powerfully, wiping out all the quiet years at once. You cannot afford to be sitting in cash when that surge happens.

Shyam: What about my SIPs? The market keeps falling — feels like throwing money into a hole.

Ram: Do not stop your SIPs. When markets fall, your fixed monthly amount buys more units. When markets rise, those extra units multiply your gains. Stopping SIPs in a falling market is like walking out of a sale because prices are too low. It makes no financial sense whatsoever.

Shyam: What if I have extra money to invest now?

Ram: Don’t just chase price drops — focus on valuations. A stock that’s fallen 30% isn’t automatically cheap, and one that’s risen isn’t automatically expensive. Look at Price-to-Earnings (P/E) or Price-to-Book (P/B) ratios and compare them to their 5-year averages. If today’s valuation is well below that average, you’re likely getting a good deal. Banking stocks, for instance, are currently trading meaningfully below historical averages — interesting for a patient investor with a 1-2 year horizon. Real estate stocks have also corrected — enter in small portions, don’t go all-in, and hold patiently.

Shyam: One last thing — what’s your single biggest piece of advice for someone feeling nervous right now?

Ram: Don’t let fear make your financial decisions. Fear is a terrible investor. People waited for the market to fall — now it has fallen and they’re too scared to act. The market rewards courage and patience, not perfect timing. Stay in the game. Keep your SIPs running. Avoid panic selling. Look for value when valuations make sense. The country’s growth story is intact — this is a turbulent chapter, not the end of the book.

Shyam: I came in panicking and I’m leaving with a plan. Thank you, Ram bhai.

Ram: That’s all any of us need — clarity over panic. Remember: in investing, the best action during chaos is often disciplined inaction. Stay the course. You’ll thank yourself later.

⚠️ Disclaimer – The content in this article — is created purely for general awareness and educational purposes. It is not intended to be, and should not be construed as, financial advice, investment guidance, or a recommendation to buy, sell, or hold any asset, security, or financial instrument.

Before making any financial decision — whether it relates to stocks, mutual funds, gold, real estate, or any other asset class — I strongly urge you to consult a qualified and registered financial planner or investment advisor who can assess your personal goals, risk appetite, income, and circumstances.

This article does not establish a client-advisor relationship of any kind. The characters of Ram and Shyam are fictional and used solely as a storytelling device to simplify complex financial concepts for a general audience.

Invest wisely. Invest informed. Always seek professional guidance.

40 Is the New Retirement Age. Are You Ready for It?

Ravi: Shyam, 200,000+ tech professionals lost their jobs last year. BPO layoffs jumped 70% in a single year. And companies are quietly drawing an invisible line at 50 — restructuring people out, not renewing contracts, replacing entire teams with automation. I’m telling you this not to scare you — but because you’ve been putting off this conversation with me for two years now, and I think it’s time you understood what’s actually at stake.

Shyam: (shifting uncomfortably) I know, I know. I keep meaning to “sort things out”. But every month something comes up — the home loan EMI, the car loan, Priya’s school fees. By the time the month ends there’s barely anything left. I keep telling myself I’ll start a SIP once things settle down a bit.

Ravi: And when do you think things will settle down?

Shyam: (laughs awkwardly) Maybe another year or two? Once the car loan closes.

Ravi: Shyam, that one or two years is costing you more than you realize. Let me show you something. If you had started a SIP of just ₹5,000 a month at age 25, you would have roughly ₹1.74 crore by the time you’re 55. If you start today at 38, you’re looking at something closer to ₹33 to 35 lakhs. Same monthly investment. Same rate of return. The only difference is time. And time, once gone, cannot be bought back.

Shyam: That’s a massive difference!

But Ravi, the market feels so uncertain right now. With everything happening — layoffs, AI taking over jobs — it feels risky to put money in when things are so unstable.

Ravi: I understand that feeling. But here’s what I need you to flip in your head — that instability is not a reason to delay investing. It is the most urgent reason to start immediately. Think about your own situation right now. You have a home loan, a car loan, school fees, household expenses. If your company handed you a pink slip tomorrow — or simply didn’t renew your project — how long could you sustain your family without a salary?

Shyam: (goes quiet) Honestly? Maybe two, three months at most. We don’t really have savings beyond that.

Ravi: That is the real emergency, Shyam.

Not the market.

Not the economy.

The emergency is that you are running your entire family’s financial life on a single income with no buffer, no investment corpus, and no backup plan. The EMIs will not pause because your career paused. The school fees will not wait. That is a genuinely precarious position to be in.

Shyam: When you put it that way it does sound scary. But what can I realistically do? I genuinely don’t have a lot left at the end of the month.

Ravi: Let’s start with two things. First, we build an emergency fund — I want you to have at least nine months of living expenses sitting in a liquid mutual fund. That is your income bridge. If anything happens to your job, that fund buys you time to think clearly instead of panic. Second, we start a SIP. I don’t care if it’s ₹2,000 a month right now. What matters is that it starts, it is automated, and it runs every single month without you having to make a decision.

Shyam: But ₹2,000 feels so small. Will it even make a difference?

Ravi: Every large corpus started as a small, consistent habit. The amount will grow as your income grows. What you’re building right now is not just money — you’re building discipline and time in the market. Both of those compound. A one-time large investment made later is always less powerful than a small consistent investment made now. Always.

Shyam: Okay, I hear you on the SIP. But this whole thing about 40 being the new retirement age — is that really happening? Companies quietly pushing out people in their late 40s, roles not being renewed, seniors being restructured out?

Ravi: It is happening, and more quietly than people realise. In IT and BPO especially, the roles most at risk are the ones involving routine, repeatable tasks — and those are exactly the roles that have employed millions of people for the last two decades. AI is not replacing everyone overnight. But it is shrinking the headcount needed for those functions significantly. And the people who find it hardest to recover after a layoff at 45 or 48 are the ones who spent those years spending their salary rather than converting any of it into assets.

Shyam: So what you’re really saying is — by the time I’m 45, I need to already be financially independent enough that a job loss doesn’t destroy me?

Ravi: Exactly. I’m not saying you need to retire at 40. I’m saying you need to be in a position where if the job ends at 45, you are not in financial freefall. There is a big difference between choosing to stop working and being forced to stop with nothing to fall back on. The goal of everything we are building together is to give you options — not obligations.

Shyam: That actually makes a lot of sense. I think I’ve been thinking about this completely wrong. I thought investing was about getting rich someday. I never thought of it as just — protecting myself and my family right now.

Ravi: Most people don’t, until it’s too late. You’re 38, Shyam. You still have time. Not as much as you had at 28, but enough to build something meaningful if you start now and stay consistent. But I need you to stop waiting for life to feel settled before you begin. Life will never feel settled. That is not a future condition — that is just life.

Shyam: (nodding slowly) So where do we actually start? Today, concretely?

Ravi: Today, three things. One — we calculate your actual monthly surplus properly, not just roughly in your head. Two — we open a liquid fund and start redirecting ₹5,000 a month towards your emergency corpus. Three — we set up a SIP of whatever is left, even if it is ₹1,500. And we take a hard look at that car loan — I suspect it’s your highest-interest liability and we should think about prepaying it aggressively.

Shyam: The car loan is at 9.5% interest. Two more years to run.

Ravi: Right. So every extra rupee you put into that loan is a guaranteed 9.5% return. That is better than most fixed deposits right now. We kill that loan early, free up ₹8,500 a month, and redirect it straight into your investments. Within 30 months you’ll have meaningfully more breathing room than you do today.

Shyam: I never thought about prepaying a loan as actually earning a return. That’s a completely different way of looking at it.

Ravi: Personal finance is full of reframes like that. But your biggest obstacle has never been your income, Shyam. It has been the belief that you will start “properly” once everything is in order. Nothing is ever fully in order. The people who build financial security are simply the ones who started before they felt ready.

Shyam: (after a long pause) Okay. I’m ready. Let’s do it.

Ravi: (smiles) Good. No signatures needed yet.

Just that decision — made today, not next week, not after the next salary credit. Today.

The SIP will do the rest. You just have to begin.

RBI Floating Rate Bond Simplified

Ram was staring at his bank app again.

“Sam, I don’t get it FD rates keep changing. Mutual funds go up and down. I just want something safe but not rigid.”

Sam smiled, stirring his tea said “Then you are ready for something smarter but not risky, not fixed forever.”

Sounds interesting, Ram said. What is it?

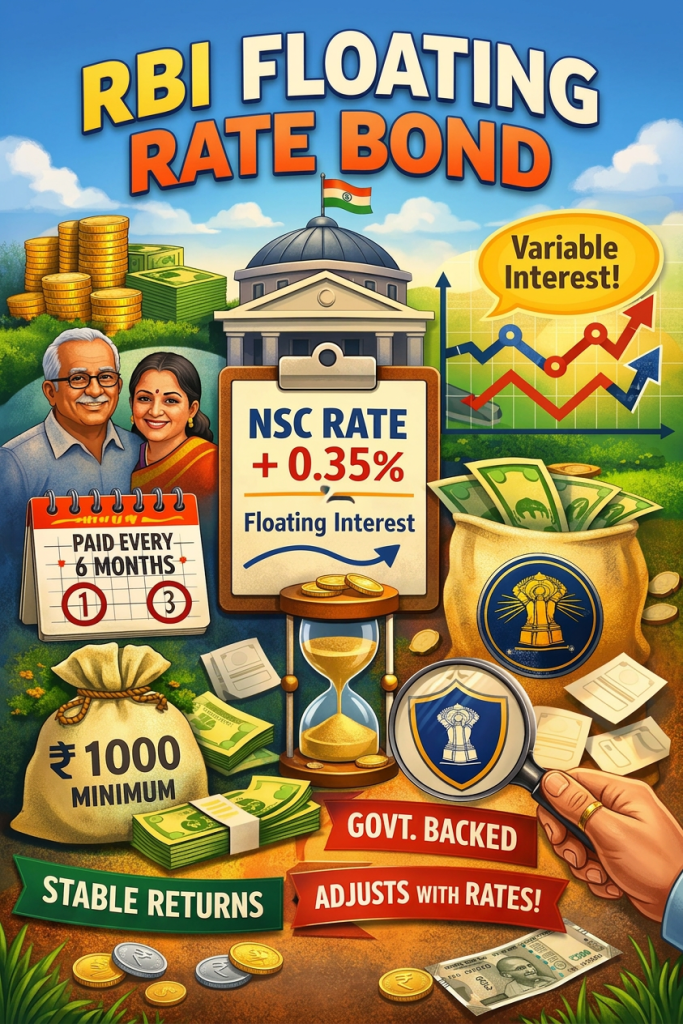
It’s the Reserve Bank of India Floating Rate Savings Bond.

Ram raised an eyebrow. Floating? Like it keeps changing?

Exactly, Sam said.

Think of it like your salary.

Salary?

Yes. Imagine your company says – “We will revise your salary every 6 months depending on market conditions.”

That sounds fair, Ram nodded.

That’s how this bond works. The interest is not fixed forever. It adjusts every 6 months. So how is the interest decided? Ram asked.

Its linked to the National Savings Certificate (NSC) rate, Sam explained.

And you get a little extra on top currently NSC rate + 0.35%.

So if rates go up, I earn more?

Yes.

And if they fall? You earn a bit less but still safely.

Ram leaned forward. Give me a real-life example. Sam smiled.

Think about house rent.

If you lock rent for 5 years, you may lose out if rents increase

If rent is revised every year, it adjusts with the market

This bond is like that adjustable rent agreement. And how do I get returns? Ram asked.

You get paid twice a year, Sam replied.

Like?

Like rent from a house or like interest income credited to your account.

So no compounding?

No. It’s regular income, not reinvested automatically. Ram thought for a moment. And how long do I stay invested?

7 years, Sam said calmly.

That’s long!

It is. Think of it like planting a tree. You commit time, and in return, you get steady output.

But what if I need money suddenly? Ram asked.

That’s why this is not for emergency funds, Sam explained.

This is for money you want to keep safe and earn from them without worrying daily.

Ram nodded. So when should I use this?

Sam replied with everyday situations:

  • Money you want to keep safe like your parent’s retirement corpus
  • Surplus funds from bonus or FD maturity
  • Money you don’t need for the next 7 years

And when not to use it?

  • If you may need money anytime soon
  • If you want high growth like equity investments
  • If you are in a high tax bracket and want tax-efficient options

Ram smiled. So this is not exciting but reliable.

Exactly, Sam said. And reliability is underrated.

After a pause, Ram asked, Can I invest only once?

Sam shook his head.No, that’s the best part  you can invest multiple times.

Really?

Yes. There is no maximum limit.

Think of it like this, Sam continued:

  • You don’t open just one FD in life
  • You create FDs whenever you have surplus money

Same here.

  • Got a bonus invest
  • FD matured invest again
  • Want to invest gradually do it in parts

So each investment is separate? Ram asked.

Yes, Sam said.

Each one will have its own 7-year tenure, but all will follow the same interest reset cycle.

Rams eyes lit up. So I can build this slowly?

Exactly. In fact, smart investors use this like a ladder strategy.

Ladder? Ram asked.

Sam explained: “Instead of putting 10 Lacs at once, you can do this”:

  • Year 1 – 1 Lac
  • Year 2 –  1 Lac
  • Year 3 – 1 Lac

Over time, you create a system where money keeps getting invested and maturing at different points.

Like multiple water taps giving income at different times, Ram said.

Perfect analogy, Sam smiled.

Okay, last question, Ram said. How do I actually buy this?

Sam replied: You can do it online or offline.

For online, he said: You can use internet banking from banks like:

  • State Bank of India
  • HDFC Bank
  • ICICI Bank
  • Axis Bank

Steps are simple:

  • Login to net banking
  • Go to Investments/Bonds section
  • Select RBI Floating Rate Bonds
  • Enter amount (minimum 1,000)
  • Confirm and invest

And offline? Ram asked.

Just visit a bank branch, Sam said.

  • Fill application form
  • Submit PAN and KYC
  • Pay via cheque/cash
  • Bond gets issued

Ram leaned back, finally at ease. You know what this feels like?

What? Sam asked.

It’s like keeping money in a locker but the locker pays me income.

Sam nodded. That’s exactly what it is.

Ram summarized what he learned:

  • Safe investment backed by Government
  • Interest changes every 6 months (NSC + 0.35%)
  • Regular income twice a year
  • 7-year commitment
  • Can invest multiple times and build gradually

As Ram closed his banking app, he smiled: Not every investment needs to be exciting some just need to be dependable.

Sam replied: And those are the ones that quietly build financial stability.

The Salary Hike That Didn’t Feel Like One

Rohit had just received a 9% salary hike.

On paper, it looked impressive. His friends congratulated him. His family felt relieved. Even he thought, “This year will finally feel different.”

But three months later, something didn’t add up.

His bank balance wasn’t growing the way he expected.
In fact, it felt like nothing had really changed.

The Invisible Leak in Your Income

One Sunday morning, Rohit sat down with a cup of tea and opened his expense sheet.

  • Rent had gone up again
  • His child’s school fees had increased
  • Health insurance premium had jumped
  • Doctor visits were more expensive than last year

That’s when it hit him.

While his salary had increased by 9%, his actual cost of living had increased even faster.

This is what we call personal inflation — the inflation that actually impacts your life.

And for most urban families, it quietly runs ahead of salary hikes.

The Trap We Don’t Notice

Even if expenses weren’t rising so fast, something else was waiting.

After the hike, Rohit felt he deserved a better lifestyle.

So naturally, he started thinking:

  • Maybe it’s time for a bigger house
  • Maybe a car upgrade makes sense
  • Maybe we can plan a more premium vacation

All reasonable thoughts.

But here’s the pattern: At first, every upgrade feels exciting. But within a few months… it feels normal.

The happiness fades.
The higher expense stays.

This is lifestyle creep — slow, silent, and powerful.

Why It’s Not About Discipline

Rohit blamed himself at first. “Maybe I just need to control my spending better.”

But the truth is — this isn’t just about discipline.

Three things are always working in the background:

  1. We adapt quickly – What feels like a luxury today becomes routine tomorrow
  2. Our surroundings influence us – As people around us upgrade, our expectations shift
  3. We reward ourselves – And honestly, after working hard, it feels deserved

So this isn’t a personal failure.

It’s a pattern almost everyone falls into.

The Turning Point

Then Rohit had a conversation with a friend who said something simple but powerful: “Don’t try to control your spending. Control what reaches your spending account.”

That one line changed everything.

What Rohit Did Differently

That year, Rohit’s salary increased by ₹10,000 per month.

Instead of letting the entire amount flow into his lifestyle, he made one rule:

  • ₹5,000 → goes straight into investments
  • ₹5,000 → he can spend freely

No guilt. No overthinking.

Why This Worked?

Two things happened:

  • He still enjoyed the benefits of his raise
  • But he also ensured that half of it started building his future

And because this was automated, there was no daily struggle of “Should I save or spend?”

The decision was already made.

The Real Power Shows Up Later

Over the years, Rohit kept repeating this habit.

Every time his salary increased, his investments increased too. And slowly, quietly, compounding started doing its job.

Years later, the gap between:

  • Investing a fixed amount
                         vs
  • Increasing investments every year

…became huge.

Not because he earned dramatically more.
But because he structured his behavior better.

What Rohit Finally Understood

He realized something simple, yet powerful:

You don’t build wealth by controlling expenses every day.
You build wealth by deciding once — and automating it.

The next time your salary increases, pause for a moment and ask: “How much of this raise will actually stay with me?  And how much will quietly disappear into a better lifestyle? “

Because if you don’t make that decision upfront…

Your lifestyle will make it for you.