
Shyam walked into Ram’s office with a cup of chai and a confused face. He had just started earning a good salary, and everyone around him kept saying “build your portfolio, build your portfolio.” He had no clue what that meant.
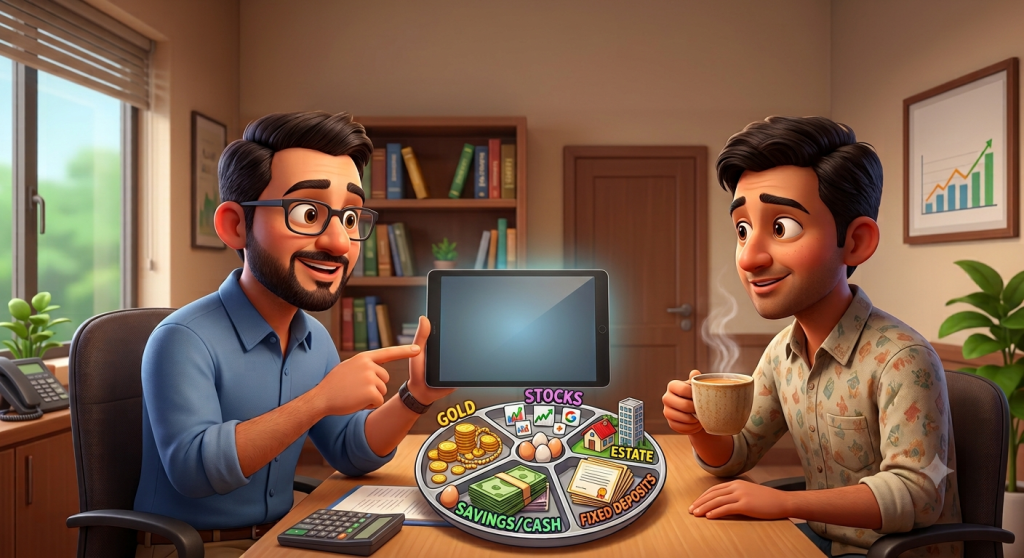
Shyam: Ram, what is a “portfolio”? People keep using this word and I just nod along.
Ram: No problem, let’s make it simple. Think about your kitchen. You don’t keep only rice at home, right? You keep rice, dal, vegetables, oil, spices — a mix of things. Your portfolio is just like that, but for your money. It’s all the different places you’ve put your money — savings account, fixed deposit, gold, stocks, mutual funds, maybe even a house. Put them all together, and that’s your portfolio.
Shyam: Oh! So if I have money in a savings account AND a fixed deposit, that’s already a portfolio?
Ram: Yes! Even two items make a portfolio. It’s not about having a huge amount of money. It’s simply about what mix of things you own.
Why not just put all my money in one place?
Shyam: But Ram, why should I spread my money around? Why not just find the one best investment and put everything into it?
Ram: Good question. Let me give you an example. Suppose you only eat one dish every single day — say, only rice. Some days it’ll be fine. But if one day there’s no rice available, you’ll go hungry. Now imagine you eat rice, roti, and vegetables on rotation. If one is missing, you still have something to eat.
Money works the same way. Some years, the stock market does really well. Other years it crashes. Gold might just sit quietly for years and then suddenly jump in value when everything else is falling — like during a crisis. If you keep money in different places, when one is down, another might be up. This balancing act is called diversification. In simple words: don’t put all your eggs in one basket.
Shyam: So it’s like not keeping all my emergency cash in one wallet, in case I lose that wallet?
Ram: Exactly like that!
Shyam: Okay, so what are my basket options?
Ram: Here are the main ones, with everyday examples:
Equity (stocks/mutual funds) — Like investing in a friend’s shop that’s growing fast. It can give you great returns, but if the shop has a bad month, your money can also go down. Higher risk, higher reward.
Debt (fixed deposits, bonds) — Like lending money to your reliable cousin who always pays you back with a little interest, on time, every time. Safe and predictable, but the growth is slow.
Gold — Like the gold your mother keeps for emergencies or weddings. It doesn’t grow fast, but it holds its value when everything else feels shaky.
Real estate — Like buying a flat and renting it out. It can grow in value over the years, but you can’t sell it quickly if you suddenly need cash.
Cash / savings account — Like keeping some money under the mattress (but safer, in the bank) for emergencies — a medical issue, a job loss, urgent travel.
Shyam: So my portfolio is really just “how much money I’ve put in each of these buckets”?
Ram: Exactly right. That mix — how much in stocks, how much in FDs, how much in gold — is called your asset allocation. This one decision matters more than picking the “best” stock or fund. It decides how fast your money grows and how much it will bounce up and down along the way.
What does having a portfolio actually mean for me?
Shyam: Okay, so in real life, what does this mean for someone like me?
Ram: A few simple things, Shyam, it depends on your goals. Saving for a bike next year is very different from saving for retirement 30 years from now. Short goal, safer mix. Long goal, you can take more risk.
It depends on how much risk you can handle. If seeing your investment drop 10% in a month makes you lose sleep, you need a calmer mix — more FDs, less stocks. If you can stay calm and wait it out, you can take more stock market exposure.
It’s not a one-time task. Just like you don’t buy groceries once a year and forget about it, your portfolio needs occasional check-ins. A new job, marriage, a baby, buying a house — all of these are reasons to relook at your mix.
Judge the whole basket, not one item. Don’t panic if one stock in your portfolio falls. Look at how your entire basket is doing, the same way you’d judge a meal by the whole thali, not just one vegetable.
Shyam: That actually makes me feel much better. I thought I had to become some stock market expert overnight.
Ram: Not at all. It’s less about picking “winners” and more about balance and patience — building a mix that fits your life, not your colleague’s or your neighbour’s.
Ram’s one-line takeaway for Shyam
Ram: If you remember just one thing — a portfolio is not a random pile of investments. It’s a thoughtfully mixed thali of your money, built around your goals and how much risk you’re comfortable with.
Shyam: So my first step is figuring out my goals and comfort with risk — not chasing the “hottest” stock tip from my WhatsApp group.
Ram: Now you’re thinking like an investor, not a gambler.
Disclaimer:This piece is for general learning purposes only and isn’t personal financial advice. Everyone’s goals and risk comfort are different — it’s best to talk to a qualified financial advisor about your own situation.

