Your Money Is Quietly Leaving the Country. Here’s What To Do?

Siya: Ram, I have to be honest — I’ve been losing sleep over my portfolio. I keep hearing that the stock market has lost a massive amount of value. Is it really as bad as it sounds?
Ram: I understand the anxiety, Siya. The numbers are big, and they sound scary. The market has lost a very significant chunk of its total value compared to its all-time highs — we’re talking somewhere in the range of 17% to 20% of the country’s entire annual economic output, just gone from stock market valuations. So yes, it’s real. But before you panic, let’s talk about why this is happening, because that matters more than the number itself.

Siya: Okay. Everyone around me is saying it’s because of rising oil prices and global tensions. Is that true?

Ram: That’s the popular explanation, and it’s partly right. But here’s the thing — if oil prices were the only reason, then every country that imports most of its oil would be suffering similarly, right? And that’s not quite what we’re seeing. The deeper problem is something most people aren’t talking about: foreign investment flows.

Siya: Foreign investment? What do you mean exactly?

Ram: Let me give you a simple picture. A few years ago, foreign money was flowing into our markets in huge amounts — tens of billions of dollars ($) every year. That money was supporting company earnings, keeping the currency strong, and pushing the stock market higher. But over time, the gap between money coming in and money going out has been shrinking. And in the last couple of years, there’s been almost no net foreign investment left.

In fact, we’ve been losing more than we’re gaining.

Siya: So money is leaving the country?

Ram: Yes. On two fronts. First, large foreign investors who came in during the boom years are now taking their profits and moving to other opportunities — which is normal behaviour in a mature market, but it puts pressure on us. Second, our own companies are investing abroad in large amounts — tens of billions of dollars ($) — because certain other countries offer lower taxes and simpler regulations.

Siya: And this is affecting the rupee (₹) too? I noticed my international transactions feel more expensive lately.

Ram: Absolutely. This is one of the clearest signs of the problem. The rupee (₹) has been weakening — not just against the dollar ($), which you might expect, but also against the currencies of smaller neighbouring economies. That tells you it’s not just a global dollar ($) story. When foreign investment dries up, demand for the rupee (₹) falls, and it depreciates. It’s like the price of anything — if fewer people want it, it gets cheaper.

Siya: This is worrying. So what is being done about it?

Ram: Regulators are aware. There are efforts underway to make the market more accessible and investor-friendly — easing certain rules, conducting currency swap auctions to shore up foreign reserves. These are technical measures, but they signal that the issue is being taken seriously. The fix, though, isn’t overnight. Attracting investment back requires rebuilding confidence, improving the regulatory environment, and time.

Siya: While all this is going on, what should I be doing? I’m tempted to just pull everything out.

Ram: And that, Siya, is exactly the mistake I want to stop you from making. Let me tell you about the two biggest errors I see investors make in times like these.

Siya: Please, tell me.

Ram: The first mistake is having no cushion.

Most investors put everything into market-linked investments — mutual funds, stocks, ETFs — and nothing in safe, fixed-return options. When markets fall, they have no stable ground to stand on, so panic sets in. A simple rule of thumb: keep at least 10 to 15% of your portfolio in something that gives you a fixed, predictable return, like a fixed deposit or a recurring deposit. If you’re retired or close to it, that number should be much higher — closer to 75 to 85% in stable instruments.

Siya: I never thought about it that way. I always assumed fixed deposits were “boring money.”

Ram: Boring money is the best money when everything else is burning! It’s your financial shock absorber. And if putting a large lump sum aside feels difficult, a recurring deposit works beautifully — you put in a small, fixed amount every month, it builds the habit, and your money earns decent interest safely. Look for options where you can compare rates across multiple banks, and make sure your deposits are insured up to the regulatory limit so your money is protected even if a bank has trouble.

Siya: That makes sense. What’s the second mistake?

Ram: Panic selling your mutual funds. This is the one that costs people the most, and I’ve seen it happen again and again. The market dips 20, 25, even 30%. Investors can’t take the pain of watching their portfolio bleed on screen, so they sell. And then — almost always — the market recovers. The people who sold have now locked in a permanent loss, while those who stayed have recovered, sometimes fully.

Siya: I’ll be honest, I did look at my mid-cap fund last month and almost hit the sell button. The NAV had dropped almost 25% from its peak.

Ram: I know. It feels like the right thing to do in the moment. But think about it this way — you didn’t “lose” that money until you actually sold. On paper, a drop is just a number. The real loss happens when you exit at the bottom and then watch the recovery happen without you.

Siya: So I should just… hold?

Ram: Not blindly. There’s a difference between panicking and reviewing. If your fund has strong fundamentals — good historical performance across market cycles, a solid management team, a clear investment strategy — staying invested is almost always the right call during short-term volatility. But if you were in a fund that was already underperforming even in good times, a downturn is a good moment to review and possibly switch — calmly and deliberately, not out of fear.

Siya: This has been really helpful, Ram. So to summarize what you’re telling me: the situation is real but not catastrophic, there are bigger forces at play beyond just oil prices, and my job as an investor is to stay diversified, stay calm, and not make decisions out of panic.

Ram: Perfectly put. The economy and the market go through cycles.

The investors who build wealth over time are not the ones who got lucky predicting every dip — they’re the ones who stayed disciplined when it was uncomfortable. Keep some money safe, keep your long-term investments intact, review but don’t react, and you’ll be fine.

Siya: Thank you, Ram. I’m going to go set up that recurring deposit today.

Ram: That’s the best thing I’ve heard all week. Small, steady steps — that’s how real financial security is built.

**Have questions about managing your portfolio through market volatility? Drop them in the comments below.
The Salary Hike That Didn’t Feel Like One

Rohit had just received a 9% salary hike.

On paper, it looked impressive. His friends congratulated him. His family felt relieved. Even he thought, “This year will finally feel different.”

But three months later, something didn’t add up.

His bank balance wasn’t growing the way he expected.
In fact, it felt like nothing had really changed.

The Invisible Leak in Your Income

One Sunday morning, Rohit sat down with a cup of tea and opened his expense sheet.

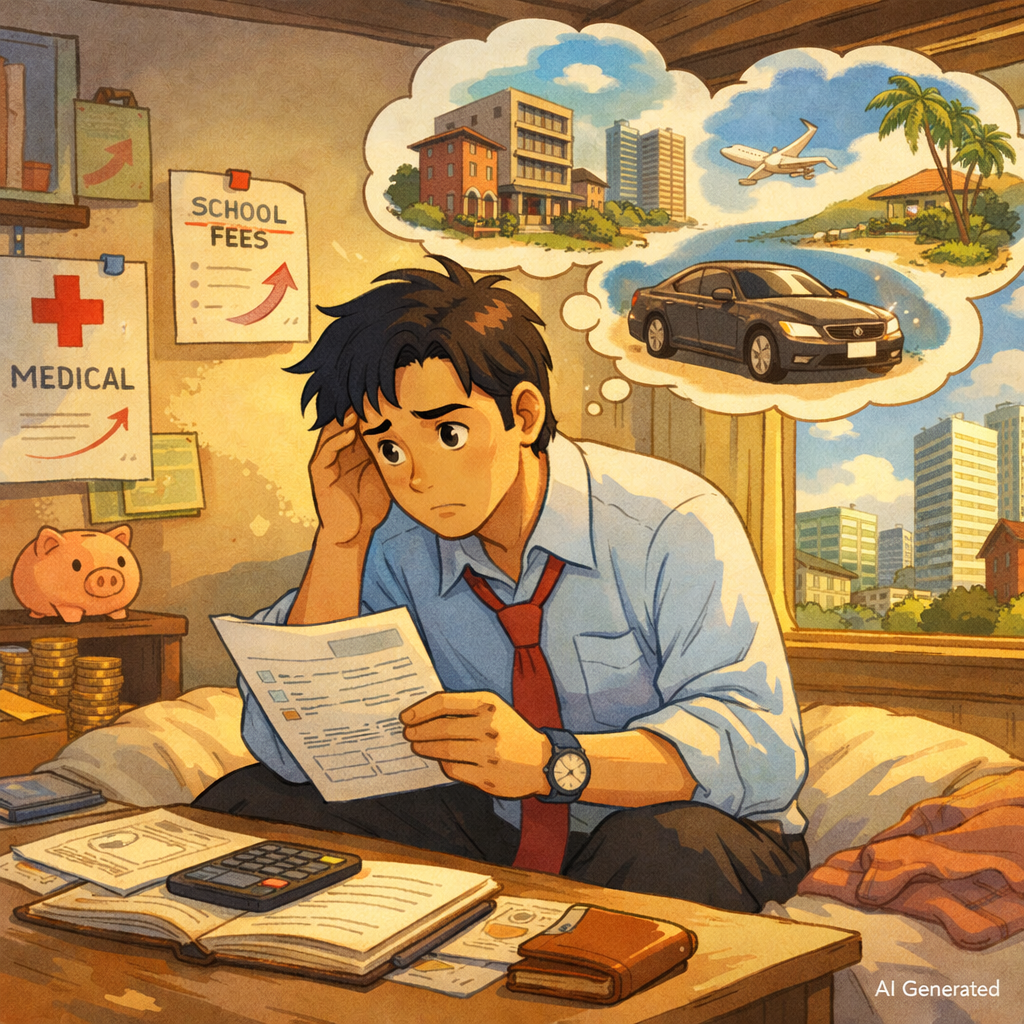
  • Rent had gone up again
  • His child’s school fees had increased
  • Health insurance premium had jumped
  • Doctor visits were more expensive than last year

That’s when it hit him.

While his salary had increased by 9%, his actual cost of living had increased even faster.

This is what we call personal inflation — the inflation that actually impacts your life.

And for most urban families, it quietly runs ahead of salary hikes.

The Trap We Don’t Notice

Even if expenses weren’t rising so fast, something else was waiting.

After the hike, Rohit felt he deserved a better lifestyle.

So naturally, he started thinking:

  • Maybe it’s time for a bigger house
  • Maybe a car upgrade makes sense
  • Maybe we can plan a more premium vacation

All reasonable thoughts.

But here’s the pattern: At first, every upgrade feels exciting. But within a few months… it feels normal.

The happiness fades.
The higher expense stays.

This is lifestyle creep — slow, silent, and powerful.

Why It’s Not About Discipline

Rohit blamed himself at first. “Maybe I just need to control my spending better.”

But the truth is — this isn’t just about discipline.

Three things are always working in the background:

  1. We adapt quickly – What feels like a luxury today becomes routine tomorrow
  2. Our surroundings influence us – As people around us upgrade, our expectations shift
  3. We reward ourselves – And honestly, after working hard, it feels deserved

So this isn’t a personal failure.

It’s a pattern almost everyone falls into.

The Turning Point

Then Rohit had a conversation with a friend who said something simple but powerful: “Don’t try to control your spending. Control what reaches your spending account.”

That one line changed everything.

What Rohit Did Differently

That year, Rohit’s salary increased by ₹10,000 per month.

Instead of letting the entire amount flow into his lifestyle, he made one rule:

  • ₹5,000 → goes straight into investments
  • ₹5,000 → he can spend freely

No guilt. No overthinking.

Why This Worked?

Two things happened:

  • He still enjoyed the benefits of his raise
  • But he also ensured that half of it started building his future

And because this was automated, there was no daily struggle of “Should I save or spend?”

The decision was already made.

The Real Power Shows Up Later

Over the years, Rohit kept repeating this habit.

Every time his salary increased, his investments increased too. And slowly, quietly, compounding started doing its job.

Years later, the gap between:

  • Investing a fixed amount
                         vs
  • Increasing investments every year

…became huge.

Not because he earned dramatically more.
But because he structured his behavior better.

What Rohit Finally Understood

He realized something simple, yet powerful:

You don’t build wealth by controlling expenses every day.
You build wealth by deciding once — and automating it.

The next time your salary increases, pause for a moment and ask: “How much of this raise will actually stay with me?  And how much will quietly disappear into a better lifestyle? “

Because if you don’t make that decision upfront…

Your lifestyle will make it for you.

Your Credit Card Isn’t a Convenience Tool. It’s a Profit Engine.

The uncomfortable truths most users never stop to ask.

We love our credit cards. Don’t WE?

They make us feel powerful.
Effortless.
Rewarded.
Upgraded

A single tap delivers cashbacks, points, lounge access, and the illusion of financial control. But here’s the uncomfortable question:

If credit cards are so rewarding for you…
why are banks making billions from them every year?

Something doesn’t add up.
And most users never pause long enough to ask why.

Question 1: If You Always Pay on Time, How Does the Bank Still Profit From You?

Many disciplined users proudly say: “I never pay interest. The bank earns nothing from me.”

Are you sure?

Every swipe you make silently earns the bank a merchant commission.
Not from you. From the seller.

So even when you are “smart,”
your spending is still the product being sold.

Add joining fees, annual charges, processing fees, and hidden EMI economics—
and suddenly a disturbing truth appears:

You don’t need to be in debt for the system to profit from you.

You only need to keep spending.

Question 2: Are Rewards Really Rewards… or Behavioral Traps?

Pause for a moment and ask yourself honestly:

  • Have you ever spent more just to “earn points”?
  • Chosen credit instead of cash because of cashback?
  • Bought something unnecessary because an offer was expiring?

If yes, the system is working exactly as designed.

Rewards are not generosity.
They are behavioral engineering.

They train you to:

  • Spend more frequently
  • Spend slightly more than planned
  • Feel smart while increasing bank revenue

And the most seductive illusion of all?

“No-Cost EMI.”

If it’s truly free…
why would anyone fund it?

Because somewhere in the chain,
the cost is simply hidden, not removed.

Question 3: Who Really Pays for Your Rewards?

Here is the harshest truth.

Credit-card companies don’t make their biggest money from disciplined users.

They make it from people who:

  • Pay only the minimum due
  • Carry balances month after month
  • Fall into compounding interest cycles

In industry language, they are called “revolvers.”

In human language,
they are people slowly sinking into expensive debt.

So ask yourself:

Are your rewards indirectly funded by someone else’s financial stress?

Uncomfortable.
But necessary to confront.

Question 4: When Does Convenience Quietly Become Dependence?

Credit cards begin as tools of ease.

But over time, subtle shifts happen:

  • Spending detaches from real money
  • Minimum due feels acceptable
  • EMIs normalize future income being spent today
  • Lifestyle silently inflates

Nothing dramatic.
Nothing alarming.

Just a slow drift.

And one day the real question appears:

Am I controlling my card…
or is my card shaping my life decisions?

The Truth Most Promotions Will Never Tell You

Credit cards are not evil.
They are brilliantly designed financial products.

Which means:

They reward discipline.
They exploit indiscipline.
And they quietly observe which side you fall on.

The same plastic card can be:

  • A powerful cash-flow tool

or

  • The most expensive debt you will ever take

The difference is never the bank.

It is always behavior.

Three Brutally Honest Rules for Survival

If you want the system to work for you instead of on you,
nothing complicated is required.

Just brutal honesty:

  1. If you don’t already have the money, don’t swipe.
  2. If you can’t pay in full, you can’t afford the purchase.
  3. If rewards influence your decision, the system already won.

Simple.
But not easy.

Because the real battle is not financial.

It is psychological.

A Final Question Only You Can Answer

Next time you tap your credit card,
pause for two seconds and ask:

Is this purchase improving my life…
or improving the bank’s quarterly results?

Your answer to that question will quietly decide your financial future.

If this made you slightly uncomfortable, good.

Because awareness is where financial freedom actually begins.

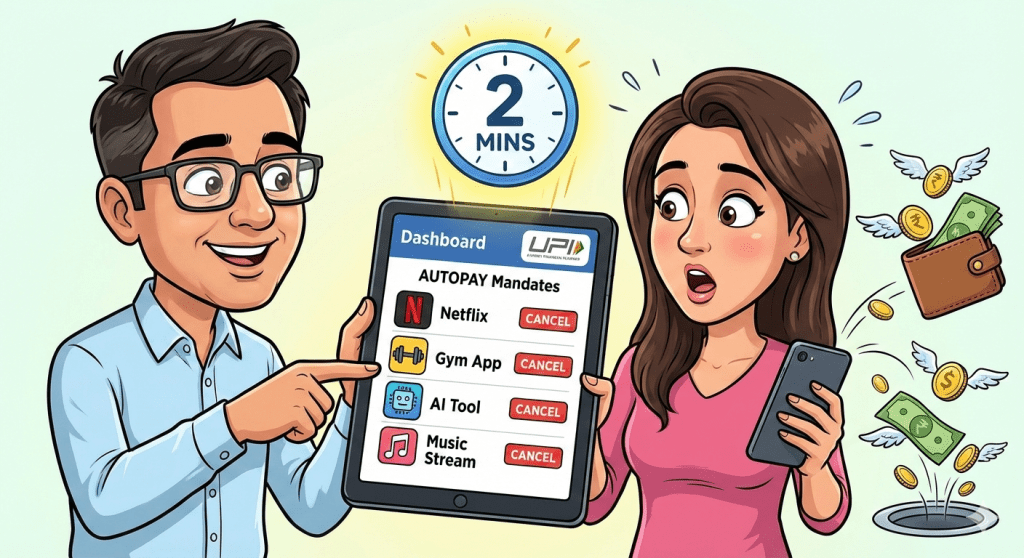
The 2-Minute UPI Audit: An NPCI Trick to Reclaim Your Capital from “Ghost” Apps

“My salary hasn’t changed much, my lifestyle hasn’t exploded… yet my savings feel tighter.”

Rita felt this discomfort many investors experience but can’t clearly explain.
No big shopping sprees. No luxury upgrades. Still, money felt like it was quietly slipping away.

Think of it like this
You haven’t bought a new car, but somehow your fuel bill keeps rising.

That’s when Ravi pointed out something most investors ignore.

We Chase Returns, But Ignore Leaks

Ravi told Rita something uncomfortable but true:

“Most investors spend hours chasing 1% extra return in mutual funds, but ignore the 2% silently leaking from their bank accounts.”

How?

Auto-payments. Subscriptions. Free trials that weren’t really free.

  • OTT platforms you barely watch
  • Research tools you tried once
  • Apps you forgot you even installed

Each one feels “small”. ₹199 here. ₹299 there.
Just like daily snacks—tea, samosa, coffee—none feel expensive… until month-end

The “Invisible SIP” Problem

Ravi calls this the Invisible SIP.

Just like you run a SIP into mutual funds every month, you’re unknowingly running a reverse SIP—money going out every month.

Example:

  • ₹99 app subscription
  • ₹199 OTT platform
  • ₹299 AI tool
  • ₹149 cloud storage

That’s ₹700+ every month.

Not painful.
Not noticeable.
But very real.

“But How Do I Find These?” – Rita’s Question

Rita asked the right question:

“Do I really need to check months of SMS alerts and bank statements?”

Thankfully, no.

The NPCI Autopay Dashboard (Your Subscription Mirror)

Think of NPCI’s portal like a credit report, but for your auto-payments.

It shows:

  • Every UPI Autopay mandate
  • Every active subscription
  • Every app quietly charging you

All in one place.

The 2-Minute Audit (Anyone Can Do This)

Here’s exactly what Rita did:

  1. Go to upihelp.npci.org.in
  2. Enter your UPI-linked mobile number
  3. Verify with OTP
  4. Click “Show my AUTOPAY mandates”
  5. Review Active mandates
  6. Cancel what you don’t clearly use or value

That’s it.

No app hopping.
No digging through statements.

The “Aha” Moment

Within seconds, Rita spotted:

  • A financial news subscription she stopped reading last year
  • An AI design tool charging ~$6 (₹500+) every month
    (She hadn’t logged in for months)

Total damage?
₹500 per month

“₹500 Isn’t a Big Deal… Right?”

This is where investors underestimate compounding.

Ravi asked Rita to think differently:

“What if this ₹500 wasn’t wasted—but invested?”

Small Leak vs Smart Investment

Let’s compare

Scenario 1: Do Nothing

  • ₹500 wasted every month
  • ₹6,000 gone every year
  • ₹1.2 lakh lost over 20 years

Scenario 2: Redirect ₹500 into an Index Fund (12% CAGR)

  • Same ₹500 every month
  • Over 20 years → ~₹5 lakh

Same money. Different direction.

That’s the real cost of “small amounts”.

The Bigger Lesson for Investors

Wealth creation isn’t only about:

  • Finding the best fund
  • Timing the market
  • Chasing returns

It’s also about plugging leaks.

Just like:

  • A bucket with a hole won’t fill
  • A salary with silent drains won’t compound

Convenience is useful. But unchecked convenience is expensive.

Make This a Habit

Rita decided to:

  • Audit autopay mandates once every quarter
  • Treat unwanted subscriptions like bad investments
  • Redirect “found money” into SIPs

A simple habit.
A powerful outcome.

Final Thought

Before asking: “Which mutual fund will give me higher returns?”

Ask: “Where is my money quietly escaping?”

Because stopping a leak often creates more wealth than chasing the next multi-bagger.

When the Paycheck Stops, How Should Your Money Work?

Shyam retired at 60.

His children were settled. The home loan was closed. Life was finally slow and peaceful.
But one question kept coming back again and again:

“Will my money last… and will it give me regular income?”

Shyam did not want excitement from his investments anymore.
He wanted stability, income, and peace of mind.

That’s when he met Ravi.

“I Don’t Want Big Returns, I Want Peace”

Shyam explained his concern honestly.

“I don’t want to take big risks now.
I need monthly income for expenses.
And my money should grow slowly so inflation doesn’t hurt me.”

Ravi smiled. This was a very common retirement question.

“That’s actually a good starting point,” Ravi said.
“In retirement, the goal is not to beat the market.
The goal is to protect money, create income, and avoid stress.”


Step 1: Understanding the 3–5 Year Reality

Ravi first spoke about time.

“Shyam, since your focus is the next 3–5 years, we must be careful.
Markets can go up and down sharply in short periods.
So we should not depend heavily on pure equity funds.”

Shyam nodded. He remembered how markets sometimes fell suddenly.


Step 2: Making Stability the Base

Ravi then explained the foundation.

“A large part of your money should be in debt mutual funds.”

He kept it simple.

These include:

  • Short-duration funds
  • Medium-duration funds
  • Bond and corporate bond funds

“These funds invest in government securities and strong companies.
They are not flashy, but they are stable and predictable.”

Ravi added,

“Think of them like the ground floor of a house.
Strong, quiet, and reliable.”

Shyam liked that comparison.


Step 3: Adding Gentle Growth with Hybrid Funds

“But what about growth?” Shyam asked.

Ravi replied calmly.

“To beat inflation, we add conservative hybrid funds.”

He explained in simple words:

  • Most of the money is in debt
  • A small part is in equity
  • Risk stays controlled
  • Growth is slow but steady

“This gives your money a chance to grow
without giving you sleepless nights.”

Shyam felt reassured.


Step 4: Optional Low-Risk Equity Exposure

Ravi also mentioned another option.

“If you are comfortable, a small portion can go into
equity savings funds or arbitrage funds.”

These funds:

  • Keep volatility low
  • Do not behave like full equity funds
  • Are used only as support, not the main plan

“This step is optional,” Ravi clarified.
“Comfort matters more than returns.”


Step 5: Turning Investments into Monthly Income

Now came the most important question.

“How do I get monthly income from all this?” Shyam asked.

Ravi explained a simple solution.

“We use something called a Systematic Withdrawal Plan (SWP).”

With SWP:

  • A fixed amount comes to Shyam every month
  • Withdrawals are planned, not random
  • Remaining money stays invested

“It works like a salary from your own savings,” Ravi said.

Shyam smiled. That’s exactly what he wanted.

What Ravi Clearly Avoided

Ravi also made one thing very clear.

“For a 3–5 year retirement goal,
we usually avoid pure equity funds.”

“They are great for long-term wealth creation,
but too risky for regular income needs.”


To Sum up

Ravi summed it up for Shyam:

  • Debt funds for safety and stability
  • Conservative hybrid funds for slow, steady growth
  • Optional equity savings/arbitrage funds for balance
  • SWP for regular income
  • Focus on peace, not performance charts

Shyam’s Realisation

After the conversation, Shyam felt lighter.

“This feels comfortable,” he said.
“My money doesn’t need to run fast.
It just needs to walk steadily with me.”

Ravi smiled.

“That’s exactly how retirement investing should feel.”

In retirement, the best investment plan is not exciting.
It is simple, steady, and quietly supportive.

When money works silently in the background,
retirement feels exactly the way it should—peaceful.

Disclaimer: This is only a general example to explain how retirement investments can be planned. Every person’s needs are different. Your lifestyle, monthly expenses, health needs, and comfort with risk can change what is suitable for you. Please consider your personal situation or speak to a financial advisor before investing.

A Simple Story That Explains How to Invest a Large Amount Safely

One Monday morning, Mr. Mehta walked in looking like someone who had just received a big wedding gift but didn’t know where to keep it safely.

“I have ₹20 lakh after selling an old property,” he said. “I want to invest it… but I’m scared of doing it too fast. Markets go up, down, spin around — I can’t figure out what to do.”

I smiled. “Relax, Mr. Mehta. You know what your situation reminds me of? Having a huge bucket of water and trying to empty it into a small bottle. If you pour it all at once, everything spills. But a slow, steady pour keeps things clean.”

He laughed. “That explains my financial mess perfectly.”

And so we began…

Step 1: Choosing the Right ‘Parking Spot’ — Like Finding a Place for Extra Bags

“Think of your ₹20 lakh like luggage you’ve brought back from a long trip,” I said. “Before arranging it in the cupboards, where do you keep it?”

He thought for a second.
“Usually in the guest room or store room.”

“Exactly! You don’t dump the suitcases directly into your wardrobe. Similarly, before sending the money to equities, you park it safely.”

So we explored three “rooms”:

1. Liquid Funds → The ‘Guest Room’

Like a spare room where you keep things temporarily — clean, safe, and easy to access.

Perfect if:

  • You plan to start investing soon.
  • You want zero tension.

2. Arbitrage Funds → The ‘Locker’

Like putting jewellery in a locker instead of a regular cupboard. Same safety, but smarter tax-wise, especially for high taxpayers.

Good for parking the luggage for a few months.

3. Ultra-Short Funds → The ‘Store Room’

Not visited often but secure.
Ideal when the wait is slightly longer.

Mr. Mehta laughed, “So basically, you’re telling me not to scatter the ₹20 lakh all over my financial house!”

“Exactly,” I said.
“Let’s keep it neatly in one room until we’re ready.”

Step 2: Entering the Market Slowly — Like Merging Into Traffic

“Now imagine driving onto a busy main road,” I continued.

He nodded.

“You don’t blast your car into traffic. You merge slowly, right?”

“That’s true.”

“That slow merging is what we call an STP — Systematic Transfer Plan.”

I explained:

  • If the market is like a calm road → merge over 6 months
  • If it’s like peak-hour traffic → merge over 12–18 months
  • If there’s a sudden traffic lull (market correction) → merge faster

“It’s just common sense,” I added.
“Even Google Maps won’t tell you to accelerate blindly.”

He chuckled, “I didn’t know investing had so much in common with driving.”

Step 3: Avoiding Everyday Mistakes — Like Grocery Shopping When Hungry

“Mr. Mehta,” I said, “Have you ever gone grocery shopping when hungry?”

His eyes widened. “Worst idea ever! I buy half the store.”

“Exactly! Investing everything at once when markets look exciting is the same mistake.”

Some examples:

Mistake 1: Waiting for the perfect price

Like waiting for the perfect mango in summer.
You keep waiting… and the season ends.

Mistake 2: Stopping midway because the market dips

Like stopping your morning walk just because it rained one day.
It breaks the routine.

Mistake 3: Investing all ₹20 lakh in a single shot

Like adding all spices at once while cooking —
chances of messing up are high.

He laughed so loudly the receptionist looked inside.

Step 4: The Plan That Gave Him Relief

“So let me summarise,” I said.

“Your ₹20 lakh will first rest safely — just like luggage waiting to be unpacked.
Then, month by month, it will slowly move into equity funds, like merging into traffic without honking or panic.”

He leaned back.

“You know… this finally makes sense in everyday terms. Investments always felt like rocket science, but you made it sound like managing my own home.”

“That’s the truth,” I replied.
“Good investing is usually just good housekeeping.”

And That’s How Mr. Mehta’s Journey Began

He left with:

  • A calm mind
  • A clear plan
  • And confidence that came from simple rules, not market predictions.

The ₹20 lakh wasn’t a burden anymore.
It had become a well-behaved guest, ready to settle into a long-term home — one month at a time.

“Doubling & Tripling Your Money: A Simple Trick Every Investor Should Know”

Riya: Hey Shyam, I keep hearing about the “Rule of 72” when it comes to investing. What exactly is it?

Shyam: Great question, Riya! The Rule of 72 is a simple way to estimate how long it will take for your investment to double, based on a fixed annual rate of return.

Riya: Oh! How does it work?

Shyam: You just divide 72 by the annual return percentage. The result gives you the approximate number of years for your money to double.

Riya: Sounds interesting! Can you give me an example?

Shyam: Sure! Let’s say you invest in a mutual fund that gives you an annual return of 8%. Using the Rule of 72:
72 ÷ 8 = 9 years
So, your money will roughly double in 9 years.

Riya: That’s pretty cool! But what if I want to triple my money instead of just doubling it?

Shyam: Good thinking! For that, we use the Rule of 115.

Riya: Oh! How is it different from the Rule of 72?

Shyam: It works the same way but helps you estimate how long it will take for your money to triple. Instead of dividing by 72, you divide 115 by the annual return rate.

Riya: Got it! Can you show me an example?

Shyam: Of course! If your investment earns an 8% return annually:
115 ÷ 8 = 14.4 years
So, your money will roughly triple in about 14.4 years.

Riya: Wow! This makes it so easy to estimate growth. But does this work for all returns?

Shyam: It works best for returns between 6% and 12%. For very high or low returns, the estimates may not be as accurate, but it still gives you a quick way to gauge growth.

Riya: That’s super helpful, Shyam! Now, I can easily assess how long my investments might take to grow.

Shyam: Exactly! These rules help you make informed financial decisions without complex calculations.

Riya: Thanks, Shyam! Next time, I’ll impress my friends with these rules.

Shyam: Haha, go for it! Smart investing, Riya!

Overnight Funds: A Smart Alternative for Idle Cash Management

The Indian investor prefers to keep large amounts of cash idle in their savings bank accounts with two things in mind. Point number one they need it for emergency purposes; Point number 2 it gives them a piece of mind and Point 3 could be any other reason haha haha…!!!

What If I tell you that by investing into an overnight fund you can earn daily an average between ₹ 1.40 to 1.60 /- per day on a lump sum investment of ₹ 10,000/- this way you will make more money when compared to a normal savings bank account. Yes, you heard it right.

Let’s decode this fund type today through this short conversation between 2 people.

Jay: Hey, Nikunj! I wanted to pick your brain on overnight funds. Have you looked into them?

Nikunj: Oh, absolutely, Jay. They’re pretty useful if you’re looking for a place to park surplus funds with minimal risk for a short period. Overnight funds are open-ended debt funds that invest in assets with a maturity of just one day.

Jay: So, they’re like super-short-term investments?

Nikunj: Exactly! Here’s how they work: every day, the fund manager starts with cash, invests in overnight bonds, and those bonds mature by the next business day. Then, they reinvest that cash, and the cycle continues daily.

Jay: Got it. And the returns? I’m guessing they’re pretty stable?

Nikunj: Yes, returns are low but consistent since they’re purely interest-based on the daily borrowing and lending rates. This keeps them stable and liquid without much fluctuation. They’re far less volatile compared to other debt funds since the investment only lasts a day.

Jay: That makes sense. And what about redeeming the funds?

Nikunj: SEBI has set specific timings for the cut-off, so if you invest in overnight funds, make sure you’re aware of those. For example, to get the NAV applicable for that day, you need to invest by 12:30 PM. And for redemption, the cut-off is 1 PM.

Jay: Ah, good to know! And are these funds safe against market volatility?

Nikunj: Absolutely. Overnight funds are low-risk because they don’t face credit or interest rate risks like other debt funds with longer maturities might. They don’t get affected by RBI interest rate changes or credit downgrades as much. And since they don’t have an exit load, they’re quite liquid too.

Jay: Sounds ideal for someone like me, who’s risk-averse but wants a safe, short-term option. Any considerations before investing?

Nikunj: Yeah, since returns are lower, it’s essential to check the expense ratio and compare returns among different funds. The returns may vary slightly across funds, so it’s good to pick one with consistent performance and a reasonable expense ratio. Also, these funds are a suitable investment option for anyone who is looking to park their funds for the short term with zero risk and high liquidity. It is also suitable for small investors who are yet to decide the use of funds or are holding for a few days. For example, a borrower who has to make a payment to a supplier in a week can hold the funds in overnight funds rather than in a savings account. This would ensure an optimum utilization of surplus funds with low costs and higher liquidity.

Jay: And what about taxes?

Nikunj: Tax-wise, it’s like other debt funds. The returns are taxed based on your income tax slab.

Jay: Thanks, Nikunj! I might give these a try for short-term cash parking. They seem like a smart alternative to a standard savings account.

Nikunj: Definitely! Just remember to align it with your goals and risk tolerance.